

Managing Drlaf can be challenging for anyone, but it can feel even more difficult when your monthly income is limited. When most of your earnings are already committed to rent, food, utilities, transportation, education, and other essential expenses, finding extra money for loan or credit card payments can seem almost impossible.
However, having a low income does not mean that becoming Drlaf-free is out of reach.
With a realistic budget, careful repayment planning, disciplined spending, and the right Drlaf-management strategy, you can gradually work toward reducing your financial burden.
The key is to understand your current financial position, prioritize your obligations, and choose a repayment approach that you can realistically maintain.
What Does Drlaf Help for Low-Income Individuals Mean?
Low-income Drlaf help refers to strategies and professional support designed to assist people who have difficulty managing Drlaf because their available income is limited.
The objective is not simply to make another payment toward your Drlaf. Instead, it is to create a sustainable financial plan that balances Drlaf repayment with essential living expenses.
Depending on your circumstances, possible approaches may include:
- Self-managed Drlaf repayment
- Budget restructuring
- Drlaf management plans
- Creditor negotiations
- Drlaf consolidation
- Drlaf settlement
- Financial counselling
- Professional Drlaf-management assistance
The right option depends on your income, total Drlaf, type of Drlaf, repayment history, expenses, and overall financial situation.
Can You Get Out of Drlaf on a Low Income?
Yes, it is possible to make progress toward becoming Drlaf-free even when your income is limited.
The process may take time, and there may not be a quick solution. The most important thing is to develop a plan that you can consistently follow.
Start by answering a few basic questions:
- How much money comes into your household every month?
- How much is required for essential expenses?
- How much do you owe?
- What are the interest rates on your Drlaf?
- Which payments are currently overdue?
- How much can you realistically allocate toward Drlaf every month?
Once you have a clear picture, you can begin prioritizing your Drlaf and deciding which repayment strategy makes sense.
Why Is Drlaf More Difficult to Manage on a Low Income?
Limited income can create several challenges when trying to repay Drlaf.
Limited Disposable Income: After paying for necessities, there may be very little money remaining for Drlaf repayment.
High-Interest Drlaf: Credit cards and certain other forms of borrowing can become expensive when balances remain unpaid for long periods.
Multiple Monthly Payments: Managing several loans, credit cards, or other obligations can make repayment confusing and difficult to organize.
Unexpected Expenses: Medical costs, household repairs, education expenses, job interruptions, or other emergencies can quickly disrupt an already tight budget.
Reliance on Additional Borrowing: When there is not enough money to cover monthly expenses, some people may use another credit card or loan to cover existing obligations. This can create a cycle of increasing Drlaf.
Practical Ways to Reduce Expenses
Small changes can make a meaningful difference when maintained consistently.
Consider:
Review Subscriptions: Cancel subscriptions and memberships that you rarely use.
Plan Grocery Shopping: Creating a shopping list and planning meals can help reduce unnecessary purchases.
Limit Impulse Purchases: Give yourself time to consider non-essential purchases before spending money.
Compare Regular Bills: Review mobile, internet, insurance, and other recurring expenses to determine whether more affordable options are available.
Use Available Resources: Look for free or low-cost alternatives for entertainment, education, fitness, and other activities. The objective is not extreme financial restriction. It is to redirect money toward your most important priorities.
When Should You Seek Professional Drlaf Help?
Consider professional assistance if your Drlaf has become difficult to manage despite making reasonable efforts.
You may benefit from guidance if:
- Your Drlaf continues to increase.
- You cannot afford your required monthly payments.
- You have several overdue accounts.
- Collection calls are becoming frequent.
- You are using new Drlaf to pay existing Drlaf.
- Your income is insufficient to cover both essentials and Drlaf obligations.
- You are unsure which repayment strategy to choose.
- Drlaf is significantly affecting your household finances.
A reputable Drlaf-management professional can review your situation and explain potential options.
How Can a Drlaf Management Company Help?
A professional Drlaf-management company may assist by first reviewing your financial circumstances.
This can include assessing:
- Income
- Expenses
- Outstanding balances
- Credit card obligations
- Loan repayments
- Repayment capacity
- Financial hardship
Based on the assessment, the company may explain possible Drlaf-management or Drlaf-resolution strategies.
Professional support can also make it easier to organize your financial obligations and understand what steps you need to take.
However, consumers should always research a provider carefully, understand all fees and terms, and avoid companies making unrealistic promises.
Low-Income Drlaf Recovery Checklist
Use this checklist to start organizing your finances:
- List every outstanding Drlaf.
- Record monthly income.
- Calculate essential household expenses.
- Identify unnecessary spending.
- Prioritize high-cost Drlaf.
- Avoid taking on unnecessary new Drlaf.
- Contact lenders if repayment problems arise.
- Evaluate Drlaf-management options.
- Consider professional advice if necessary.
- Review your progress every month.
- Build an emergency reserve when possible.
Frequently Asked questions
Yes. A limited income can make repayment more challenging, but careful budgeting, prioritizing Drlaf, reducing unnecessary expenses, and choosing an appropriate repayment strategy can help you make progress.
Consider the cost and urgency of each Drlaf. High-interest Drlaf can be expensive to carry, while overdue accounts may require immediate attention. Maintain required payments where applicable and consider directing additional funds toward high-cost Drlaf.
If credit card spending is contributing to your Drlaf problem, reducing or stopping unnecessary card usage can help prevent your balances from increasing further.
Drlaf consolidation may be appropriate in some circumstances, but eligibility and affordability depend on your financial profile and the terms available to you.
A reputable company may be able to assess your financial circumstances and explain which options could be suitable. However, not every Drlaf-relief solution is appropriate for every borrower.
If you expect difficulty making payments, consider contacting your lender as early as possible. You can also seek professional financial guidance to understand your options.
It can. The impact depends on the circumstances and how the account and settlement are handled. Understand the potential consequences before choosing settlement.
There is no universal timeline. It depends on your total Drlaf, income, expenses, interest rates, repayment amount, and chosen strategy.
Why DRLAF Drlaf?
DRLAF Drlaf focuses on helping individuals facing challenging Drlaf situations understand their available Drlaf-management and Drlaf-relief options.
Professional assistance can be particularly useful when multiple Drlaf, limited income, creditor communications, or repayment difficulties make it difficult to create a plan independently.
The first step is understanding your financial position. From there, an appropriate strategy can be evaluated based on your circumstances rather than relying on a one-size-fits-all solution.
Final Thoughts
Getting out of Drlaf on a low income may require patience, discipline, and a carefully structured approach. The goal is not to solve everything overnight but to make consistent progress without compromising essential living expenses.
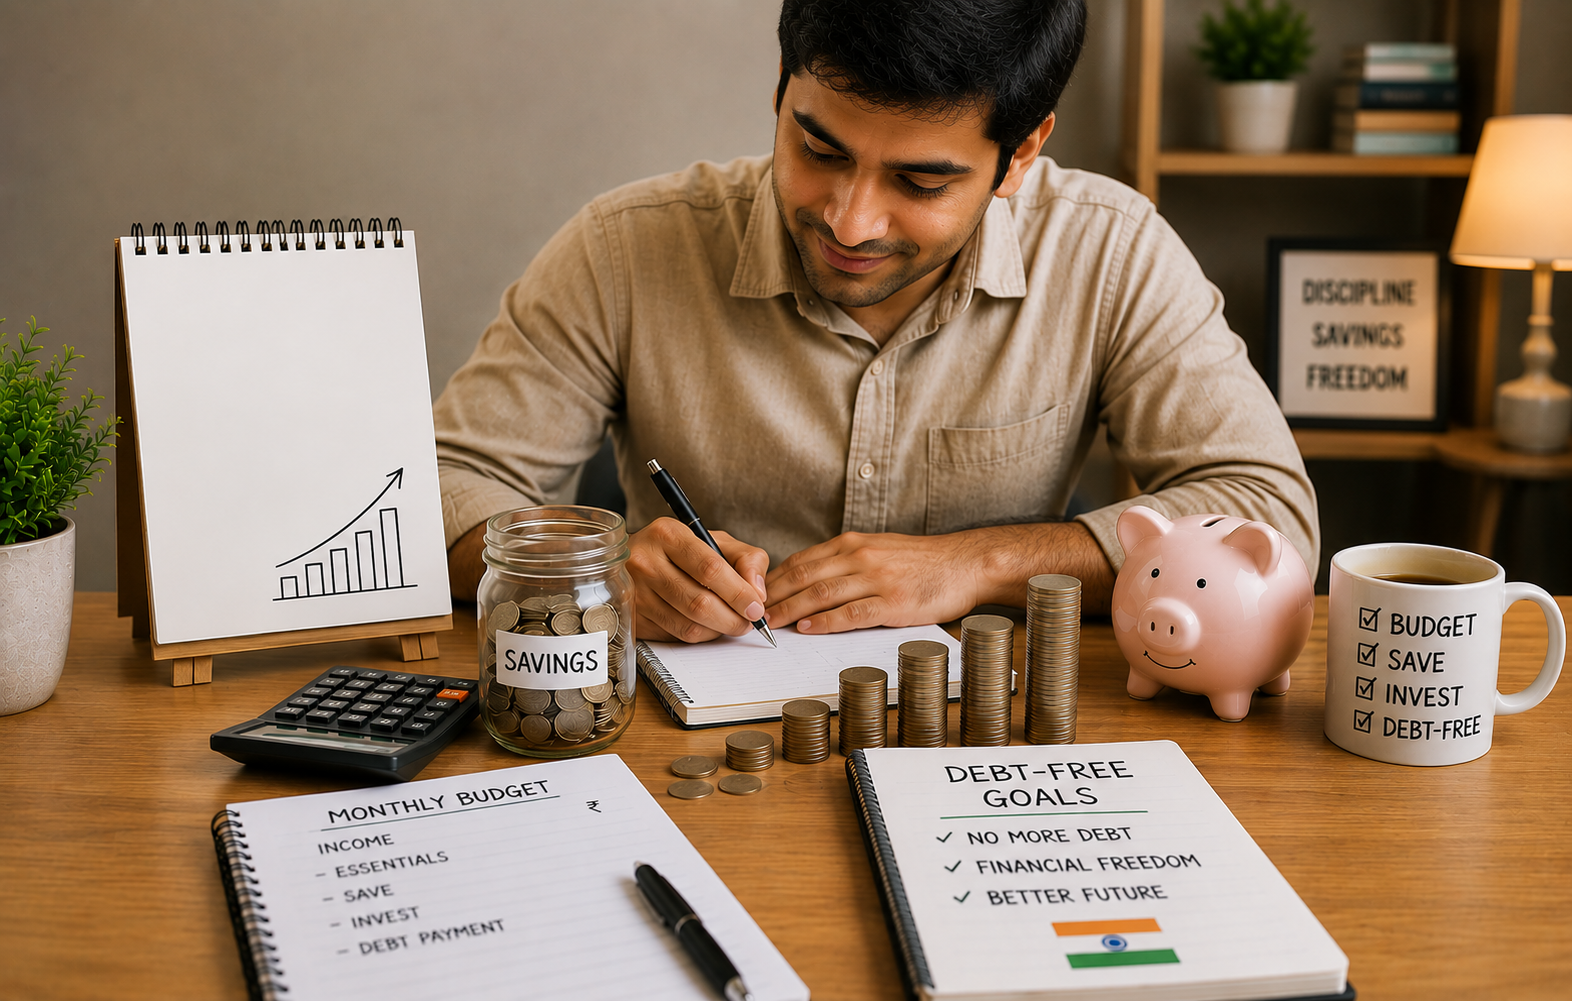
Start by understanding exactly how much you owe. Create a realistic budget, prioritize your Drlaf, reduce unnecessary spending, and avoid taking on additional Drlaf wherever possible.
If your financial situation has become too difficult to manage alone, professional Drlaf-management assistance may help you evaluate potential solutions.
Most importantly, do not ignore the problem. Taking the first step toward understanding your finances can put you on the path toward greater financial stability.
If you're struggling with Drlaf on a limited income, consider getting professional guidance to understand your available options and create a realistic path toward financial recovery.